1
Drake Manual Supplement: Fiduciaries
Tax and Payments
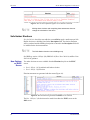
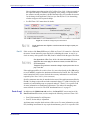
Figure 6: From the SCH screen, select “011” from the drop list and
show your computation in the text box
For more information, see the IRS instructions for Form 1041.
Payments
Generally, an estate or trust must pay estimated income tax if it expects to owe $1,000
or more in tax, and expects the withholdings and credits to be less than the smaller of:
•
•
90% of the tax shown on the current-year return
100% of the tax shown on the prior-year return
NOTE
Estimated
Payments
and Amount
Applied from
Prior Year
Estates are not required to pay estimated tax within the first two years
of creation.
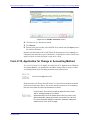
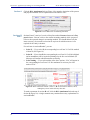
Drake offers several ways to enter estimated tax amounts that were applied from the
prior-year tax return and paid in the current year. The preferred method is to enter
quarterly and total amounts on the ES screen, accessible from the Other Forms tab.
•
•
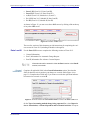
Estimated Taxes — Enter the estimated taxes due for next year on the right side
of the screen in the Estimate Amt fields. From the ES Code drop list, choose how
you want payment vouchers to be printed with the return. (Press F1 to view the
full code descriptions.)
Overpayment of Taxes — For overpayment of taxes, make a selection from the
OP Code drop list and enter the amount of the overpayments in the applicable text
boxes on the right side of the screen. (Press F1 to view the full code descriptions.).
Do not include on Form 1041 any estimated tax paid by an individual before death. Instead, include the payments on the decedent’s
final income tax return.
NOTES
For details on using the enhanced ES screen for filing federal estimated taxes, and on e-filing and paying state estimated taxes, see
“Estimated Taxes,” beginning on page 183 of the Drake Software
User’s Manual: Tax Year 2014.
See Form 1041 instructions for more information on estimated
taxes.
Estimated
Payments
Allocated to
Beneficiaries
Tax Year 2014
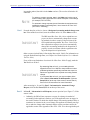
Form 1041-T, Allocation of Estimated Tax Payments to Beneficiaries, is used to elect,
under section 643(g), to have part of an estate or trust’s estimated tax payments (but
not income tax withheld) treated as having been made by the beneficiary or beneficiaries.
21